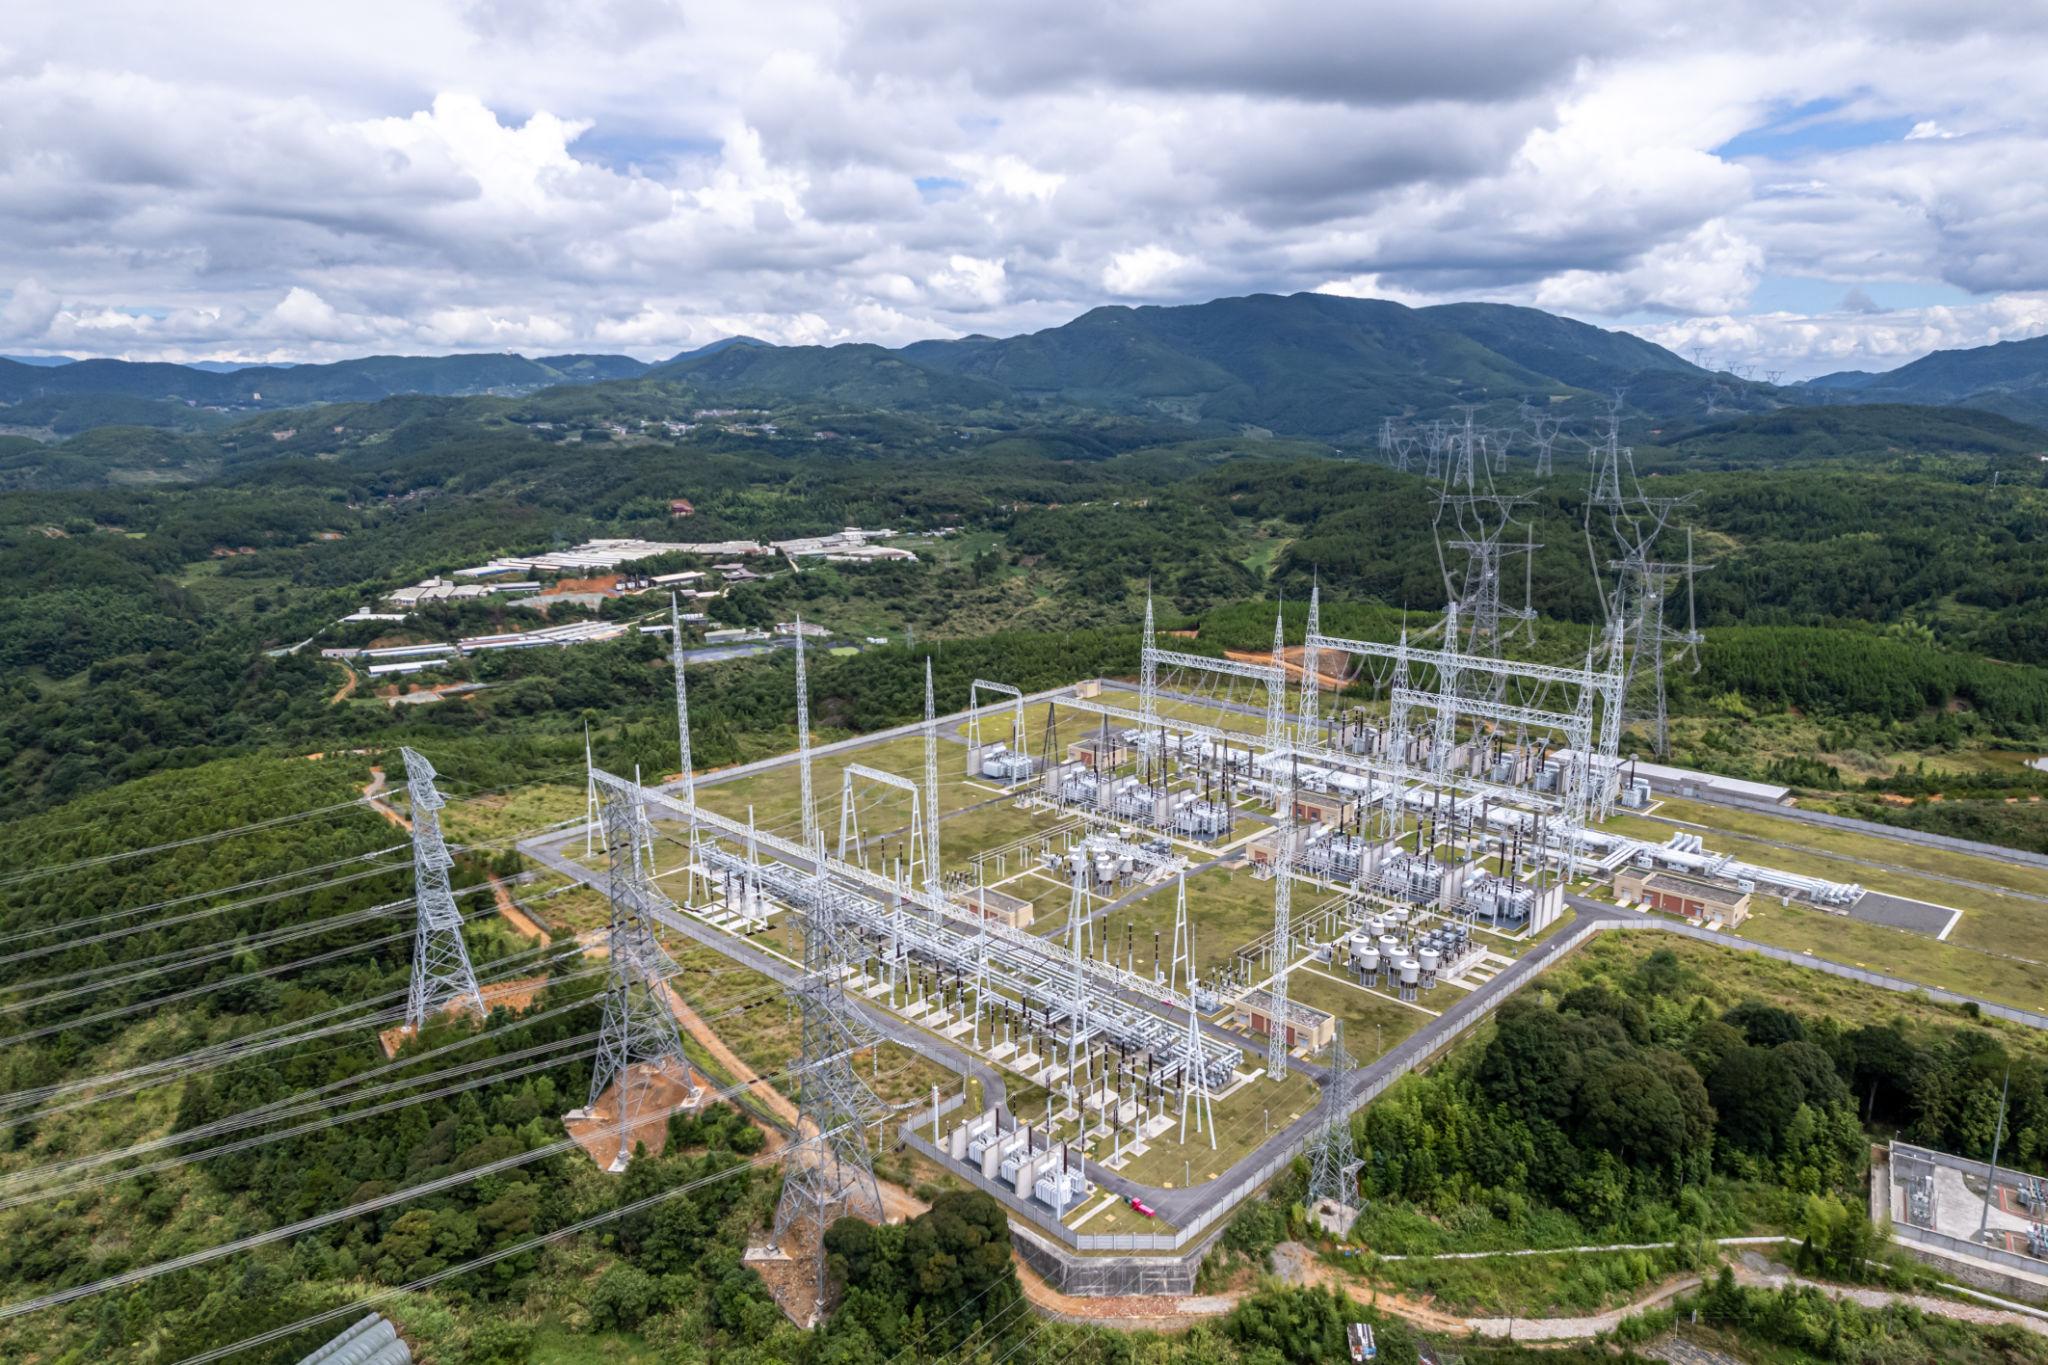
Energy transition asset management directly influences capital allocation decisions by forcing organizations to evaluate assets not just on current performance, but on their projected value across a decarbonizing energy system. For asset-intensive utilities and energy companies, this means investment decisions must account for regulatory trajectories, technology disruption, and shifting demand patterns simultaneously. The sections below unpack the key questions shaping how capital gets deployed in this environment.
What factors are reshaping capital allocation in energy transition asset management?
The primary factors reshaping capital allocation in energy transition asset management are regulatory pressure, technology cost curves, and the accelerating obsolescence of fossil-fuel-dependent infrastructure. Together, these forces are compressing the investment horizon for conventional assets while increasing the urgency of renewables, grid flexibility, and digitalization spending.
In practical terms, this means capital planning can no longer follow traditional five-to-ten-year cycles built around steady-state assumptions. The regulatory environment in most European markets, and increasingly in the Middle East and Asia, is shifting faster than asset depreciation schedules. Carbon pricing mechanisms, capacity market reforms, and grid decarbonization mandates are all repricing risk for long-lived assets in ways that were not modeled in previous investment frameworks.
At the same time, the cost of renewable generation, battery storage, and digital grid management tools has dropped substantially over the past decade. This changes the competitive economics of capital deployment: spending that once required a long payback period to justify now competes favorably against conventional alternatives. For capital allocation committees, this means the baseline assumptions underpinning investment cases need to be revisited more frequently and with greater scenario sensitivity than before.
How does asset lifecycle stage affect energy transition investment priorities?
Asset lifecycle stage is one of the most decisive factors in energy transition investment prioritization. Assets in early lifecycle stages warrant different capital treatment than aging infrastructure approaching end-of-life, because the energy transition creates a divergence between technical lifespan and economic useful life that did not exist at this scale before.
For assets in their early or mid-lifecycle, the key question is whether the asset’s design and capability are compatible with the direction of the energy system. A gas peaker plant commissioned in 2015 may have thirty years of technical life remaining, but its economic value is already being challenged by storage economics and demand flexibility programs. Capital investment in such assets needs to be evaluated against the risk that the asset becomes uneconomic before it is fully depreciated.
For aging assets approaching end-of-life, the energy transition creates a genuine decision point: invest to extend life, replace with a like-for-like successor, or exit the asset class entirely and redirect capital toward transition-aligned alternatives. Getting this decision right requires an honest assessment of both the asset’s residual value and the strategic direction of the broader portfolio. Organizations that default to like-for-like replacement without interrogating the transition context are locking in capital commitments that may not age well. This is where strategic asset management expertise becomes essential to ensuring decisions are grounded in long-term value rather than short-term convenience.
What is stranded asset risk and how does it influence capital decisions?
Stranded asset risk is the risk that an asset loses its economic value before the end of its expected technical life, typically because of regulatory change, market disruption, or shifting demand. In energy transition asset management, this risk is a central consideration in any capital decision involving long-lived infrastructure tied to fossil fuels or carbon-intensive processes.
The influence on capital decisions is direct and significant. When stranded asset risk is high, the effective investment horizon shortens. A conventional power plant or gas distribution asset that carries meaningful stranding risk cannot be evaluated on the same return assumptions as an asset with a predictable, policy-supported revenue stream. This forces capital allocation teams to apply scenario analysis and risk-adjusted return modeling rather than relying on single-point forecasts.
Practically, organizations managing stranded asset risk well tend to do a few things consistently. They segment their portfolio by transition exposure, identifying which assets are most vulnerable to early obsolescence. They set explicit thresholds for capital reinvestment in high-risk asset classes. And they build flexibility into their investment structures, favoring modular or shorter-commitment capital where possible over large, long-duration bets in areas of high uncertainty.
How do utilities balance reliability investment with decarbonization spending?
Utilities balance reliability investment with decarbonization spending by treating them as complementary rather than competing priorities, structured through a portfolio approach that sequences capital deployment based on risk, regulatory obligation, and strategic timing. The tension is real, but it is manageable with the right framework.
Reliability investment cannot be deferred without consequence. Grid stability, asset availability, and service continuity obligations are non-negotiable for regulated utilities, and regulators in most jurisdictions hold firms accountable for these outcomes regardless of transition pressures. This means a baseline of reliability-focused capital is always required.
The discipline lies in identifying where reliability investment and decarbonization investment overlap. Grid modernization spending, for example, often delivers both outcomes simultaneously: upgrading aging transmission infrastructure improves reliability while also enabling higher penetration of variable renewables. Smart metering, advanced protection systems, and grid automation all sit in this dual-benefit category. Prioritizing these investments first allows utilities to make progress on decarbonization without sacrificing the reliability performance that regulators and customers expect.
Where genuine trade-offs exist, the decision should be driven by a clear articulation of risk tolerance and regulatory exposure. Deferring reliability investment to fund decarbonization is rarely defensible if it increases the probability of service disruption or regulatory penalty. The sequencing and sizing of capital across both priorities is where experienced judgment matters most.
What role does performance benchmarking play in energy capital planning?
Performance benchmarking plays a critical role in energy capital planning by providing the external reference points needed to distinguish between underperformance that warrants investment and performance levels that are already competitive. Without benchmarking, capital allocation decisions are made in a vacuum, with no reliable way to assess whether spending is addressing a genuine gap or simply reinforcing the status quo.
In the context of energy transition asset management, benchmarking serves two specific functions. First, it helps identify where assets or operational processes are lagging behind industry best practice in ways that affect transition readiness. An organization that benchmarks its asset health data quality, for example, may discover that its ability to make informed capital decisions is itself constrained by information gaps that need to be addressed before larger investment choices can be made confidently.
Second, benchmarking provides the evidence base for investment cases. When capital allocation decisions need board or regulatory approval, comparative performance data is a far more persuasive foundation than internal assessments alone. Showing that a specific asset class or operational capability is performing in the bottom quartile of a credible peer group creates a clear rationale for investment that is difficult to challenge.
How should asset-intensive organizations structure their capital allocation framework for the energy transition?
Asset-intensive organizations should structure their capital allocation framework for the energy transition around four core elements: portfolio segmentation by transition exposure, scenario-tested investment cases, a clear governance process for trade-off decisions, and dynamic review cycles that match the pace of external change rather than defaulting to annual planning rhythms.
Portfolio segmentation is the starting point. Not all assets carry the same transition risk or opportunity profile, and treating the portfolio as a uniform block leads to misallocated capital. Segmenting by asset class, lifecycle stage, and transition sensitivity gives decision-makers a structured view of where capital is most and least at risk.
Scenario testing matters because the energy transition is not a single trajectory. Regulatory timelines shift, technology costs move faster or slower than expected, and demand patterns evolve in ways that are difficult to predict with precision. Investment cases that hold up across a range of plausible scenarios are more defensible than those optimized for a single base case. Building this discipline into the standard investment approval process is a structural change that pays dividends over time.
Governance and review cadence are often underestimated. Many organizations have the analytical capability to produce good capital plans but lack the governance structures to make timely decisions when circumstances change. A capital allocation framework that includes defined escalation paths, clear accountability for portfolio-level trade-offs, and a review cycle that responds to material external changes rather than waiting for the next annual plan will consistently outperform one that does not.
How OHROS supports energy transition capital allocation
We work with asset-intensive energy and utility organizations to bring structure and rigor to capital allocation decisions at exactly the moments when the transition makes them most complex. Our approach combines decades of global benchmarking experience with practical diagnostic methodology, so clients make investment decisions based on evidence rather than assumption. Our team brings together specialists with deep sector knowledge across utilities, infrastructure, and energy markets worldwide.
- Portfolio transition assessment: We segment client asset portfolios by transition exposure and lifecycle stage, providing a clear view of where capital is at risk and where investment will generate the most durable returns.
- Scenario-based investment planning: We build and stress-test investment cases across multiple energy transition scenarios, ensuring capital commitments are defensible under a range of regulatory and market conditions.
- Performance benchmarking: We draw on our proprietary benchmarking library to position client performance against credible peer groups, identifying gaps that justify investment and areas where capital reallocation makes more sense.
- Capital governance design: We help organizations build the governance structures and review processes needed to make timely, well-informed capital decisions as transition conditions evolve.
If your organization is navigating capital allocation decisions in the context of the energy transition and wants a structured, evidence-based approach, get in touch with our team to discuss how we can help.